If you are short of money before payday, two options usually come up: a salary advance loan (a quick, short-term loan) or a regular personal loan. Both are unsecured loans, but they are built for very different needs. Choosing the wrong one can cost you more than necessary. Here is a simple comparison.
The short answer
- For a small amount needed for a few weeks — rent before salary day, a medical bill, a repair — a salary advance / quick loan is usually simpler.
- For a larger amount — a wedding, home renovation, consolidating debts — that you need to repay over months, a personal loan with EMIs is usually better.
Side-by-side comparison
| Salary advance / quick loan | Personal loan | |
|---|---|---|
| Typical amount | ₹2,000 – ₹30,000 | ₹50,000 – ₹10 lakh or more |
| Tenure | 15 – 45 days | 12 – 60 months |
| Repayment | One single repayment | Monthly EMIs |
| Interest (per year) | Higher (34% – 54% p.a. with Quick Loan) | Lower, depends on profile |
| Processing fee | 10% – 20% + GST | Usually a smaller percentage |
| Best for | Short, temporary cash gap | Large, planned expenses |
Personal loan figures are general market ranges for comparison only.
Why a quick loan has a higher rate — and why that is not the whole story
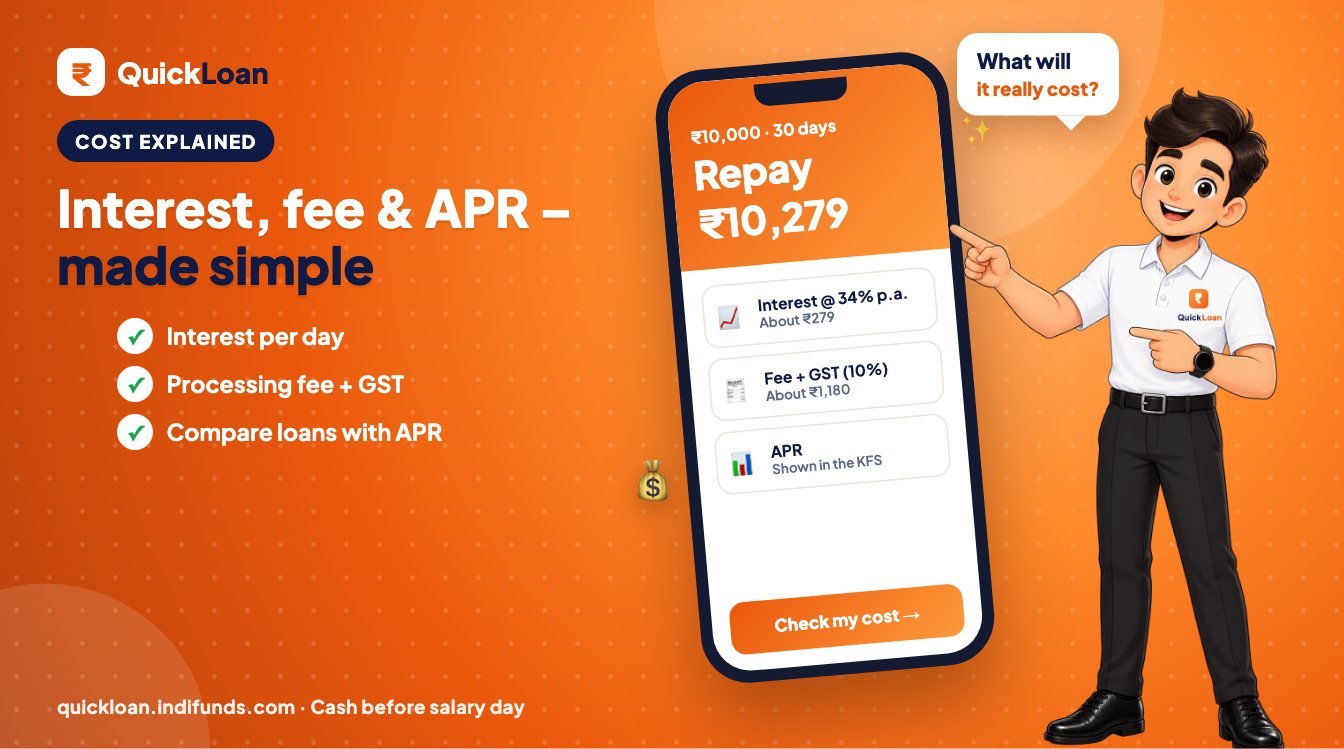
A quick loan's yearly interest rate looks high, but you borrow for only a few weeks, so the rupee cost of interest is small. For example, ₹10,000 for 30 days at 34% per year is about ₹279 in interest.
What matters more for a short loan is the processing fee, because it is charged once on the amount. That is why you should always compare the total amount you repay (and the APR shown in the Key Fact Statement), not just the interest rate. Our article on quick loan interest, fees and APR explains this with examples.
When a salary advance loan is the better choice
- You need ₹30,000 or less
- You can repay it from your next salary
- You want a simple online process and one repayment instead of EMIs
- You don't want to take on a long-term loan for a short-term problem
When a personal loan is the better choice
- You need a larger amount
- You need several months to repay
- The expense is planned (wedding, education, renovation)
- You want a lower yearly rate and are comfortable with monthly EMIs
A common mistake to avoid
Some people take a short-term loan for a large, long-term need and then keep taking new short loans to repay the old ones. This "rollover" makes the fees add up quickly. If you can't repay within 45 days, a short-term loan is not the right product — speak to us about other options instead.
Your employer is not involved
A salary advance loan from Quick Loan is not an advance from your company. The loan is given by an RBI-regulated lending partner, so you don't need to ask HR or your manager, and your employer is not informed by us.
The bottom line
Use a salary advance / quick loan for small, short and urgent needs you can repay on payday. Use a personal loan for bigger, planned expenses that need time to repay. If a quick loan fits your need, check your eligibility or read about the salary advance loan.
Frequently asked questions
Is a salary advance loan cheaper than a personal loan?
For a few weeks the rupee cost of a salary advance can be small, but its yearly rate and fee percentage are higher. For larger amounts over months, a personal loan is usually cheaper.
Do I pay EMIs on a salary advance loan?
No. A salary advance / quick loan is usually repaid in one single repayment after 15 to 45 days.