When salary day is still a week away and a bill can't wait, many salaried people look for a quick loan: a small amount, taken for a few weeks, and repaid in one go when the salary arrives. This guide explains how a quick loan for salaried employees works, who can get one, what it really costs and how to apply safely.
What is a quick loan?
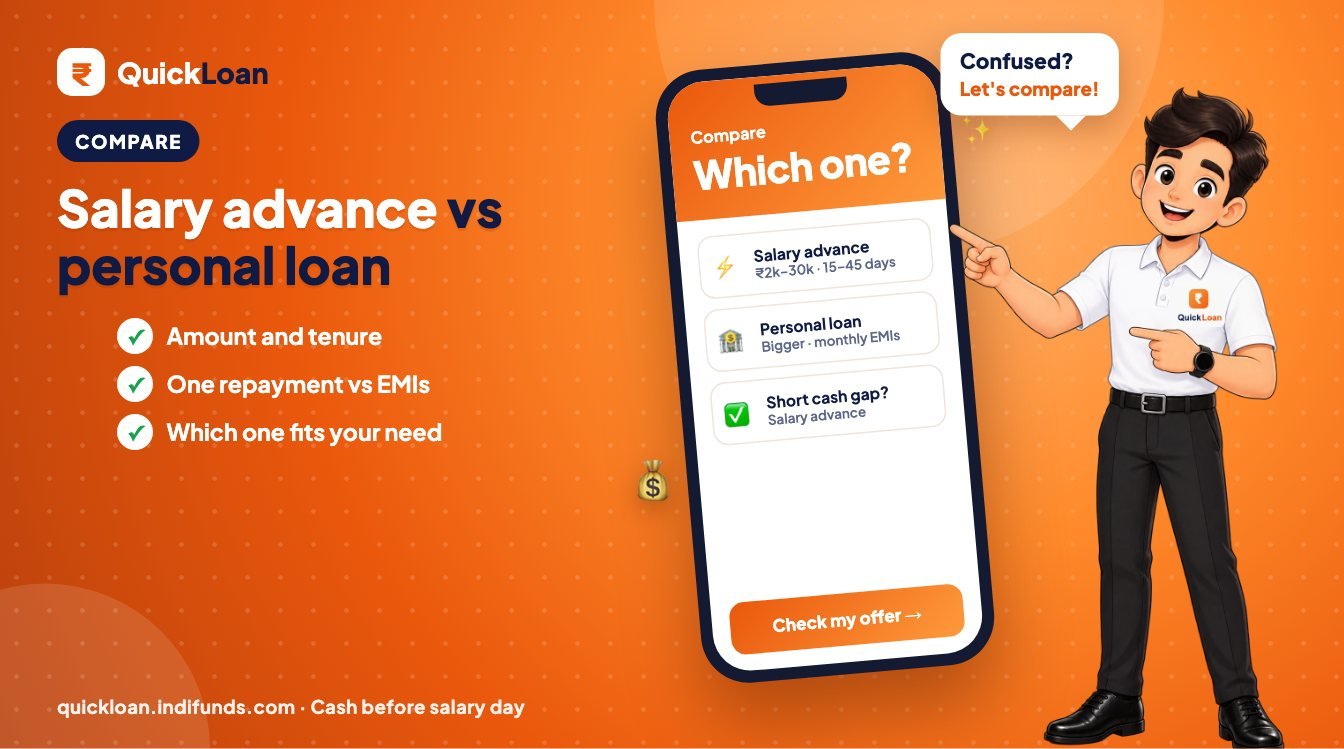
A quick loan is a short-term, unsecured personal loan for a small amount. With Quick Loan, salaried people can request ₹2,000 to ₹30,000 and repay it in 15 to 45 days, usually on their next salary date. There is nothing to pledge, no guarantor and no branch visit — the application is online.
It is different from a regular personal loan. A personal loan is usually a larger amount repaid in monthly EMIs over one to five years. A quick loan is meant for a temporary cash gap and is closed with a single repayment.
When does a quick loan make sense?
A quick loan is useful when the need is genuine, small and short, and you are sure you can repay it from your next salary. Common examples:
- Rent or a rental deposit due before salary day
- Doctor visits, tests or medicines
- School or exam fees with a deadline
- A bike, phone or laptop repair you need for work
- Electricity or credit card dues, to avoid a late penalty
- Urgent travel for a family need
It is not a good idea for long-term spending, to repay another loan again and again, or for an amount you cannot comfortably repay within 45 days.
Who can apply?
The basic criteria for a quick loan through Quick Loan are:
- You are a salaried employee, aged 21 to 58 years
- Your CIBIL score is 700 or more
- No late EMI or card payments in the last 6 months
- No settled or written-off loan in the last 18 months
- Not more than 10 loan enquiries in the last 30 days
The loan is not available in Arunachal Pradesh, Assam, Manipur, Meghalaya, Mizoram, Nagaland, Tripura, Sikkim, Jammu & Kashmir and West Bengal. Meeting the criteria does not guarantee approval — the lender makes the final decision after its own checks.
You can check these points in under a minute with our eligibility checker.
What does a quick loan cost?
Short-term loans are priced differently from long-term loans, so it is important to look at the total amount you repay, not just the rate.
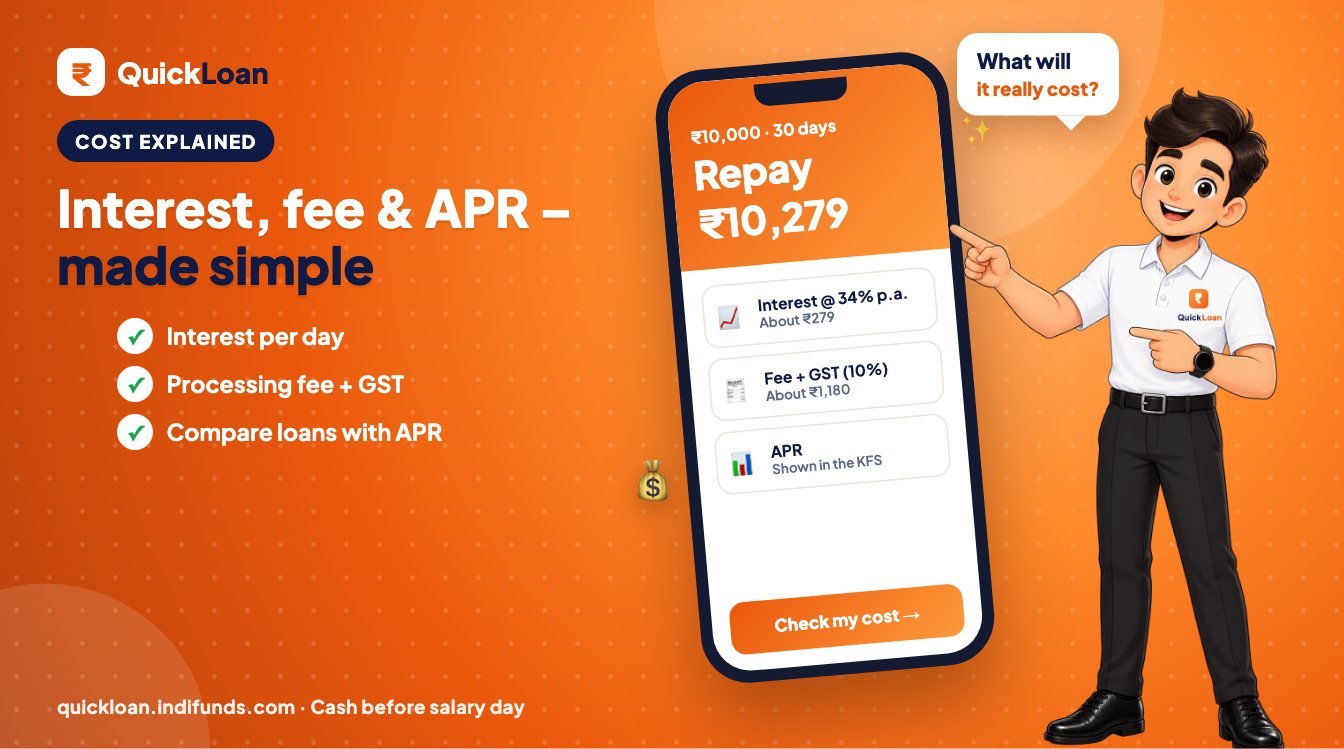
- Interest: 34% to 54% per year, charged only for the days you borrow
- Processing fee: 10% to 20% of the loan amount, plus 18% GST — usually deducted from the loan amount
Example: a loan of ₹10,000 for 30 days at 34% per year costs about ₹279 in interest. The processing fee at 10% plus GST is about ₹1,180. You repay about ₹10,279 on the due date. These are illustrative figures — your actual rate, fee and total are shown in the lender's Key Fact Statement (KFS) before you accept.
Try your own numbers on the loan calculator.
How to apply, step by step
- Answer six quick questions — mobile number, loan amount, monthly salary, city, approximate CIBIL score and your name. Most answers are just taps.
- Complete online KYC with the lending partner using your PAN, Aadhaar and salary bank account.
- Read the Key Fact Statement — check the amount, interest, fee, APR, due date and total repayment.
- Get the money in your bank account after approval.
- Repay on time on the due date, usually your salary day.
See the full journey on how it works.
Documents you need
Only three things: your PAN, your Aadhaar and the bank account where your salary is credited. You do not upload any documents on the Quick Loan form; KYC happens online on the lender's secure page. Read more in quick loan documents required.
Tips before you borrow
- Borrow only what you need — a smaller loan means a smaller fee and less interest.
- Match the tenure to your salary date so repayment is comfortable.
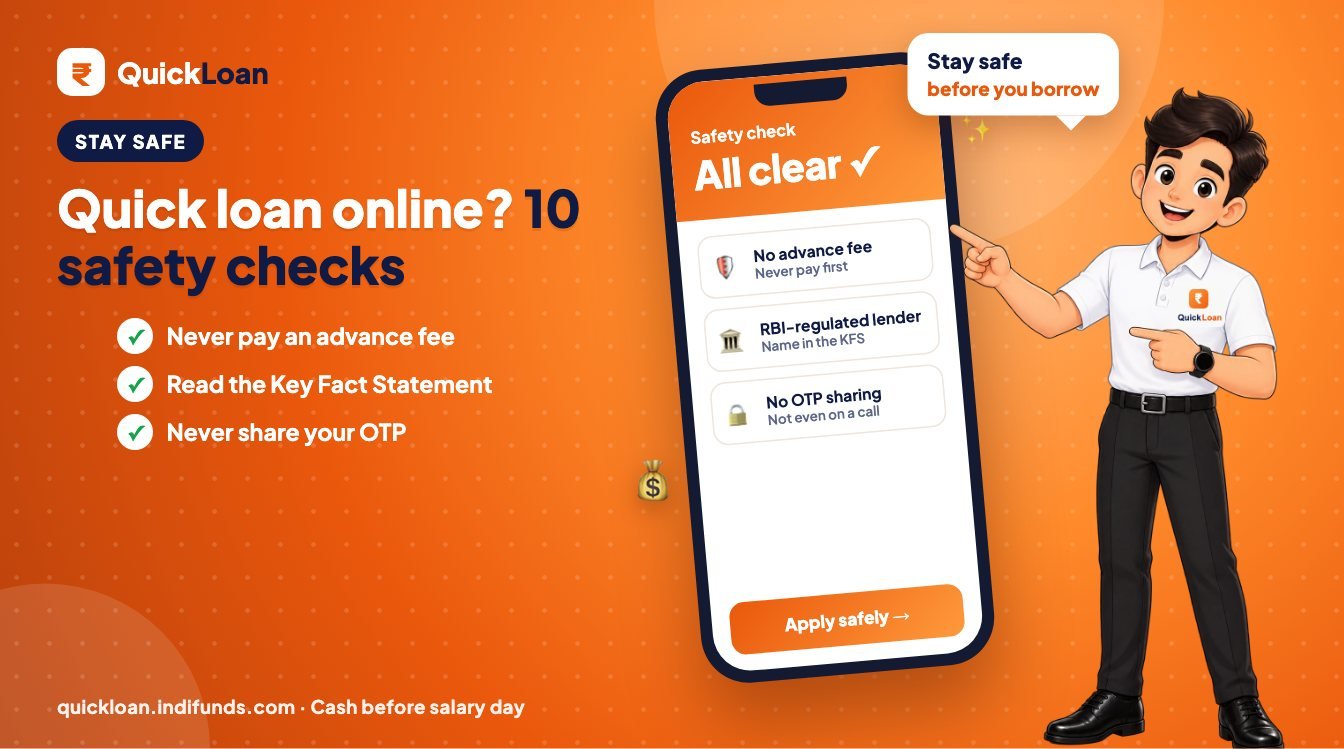
- Never pay anyone in advance. Quick Loan and its RBI-regulated lending partners never ask for any fee before a loan.
- Repay on time. Late payment adds charges and can lower your CIBIL score; on-time repayment helps it.
The bottom line
A quick loan for salaried employees can bridge a short cash gap without a long application or monthly EMIs — as long as you borrow a small amount, understand the total cost and repay it on time. If your CIBIL score is 700 or more, you can apply in about 2 minutes.
Frequently asked questions
Can a salaried person get a quick loan with a low CIBIL score?
This quick loan needs a CIBIL score of 700 or more. If your score is lower or you are not sure, apply anyway – we will show you another option.
How much quick loan can I get on my salary?
Between ₹2,000 and ₹30,000. The lender decides the final amount based on your salary, credit score and repayment history.
Is a quick loan the same as a salary advance from my company?
No. It is a short-term loan from an RBI-regulated lending partner. Your employer is not involved.